
Winter Storm Power Outages: How Parametric Insurance Helps Businesses Recover Faster
January 23, 2026
How Adaptive’s GridProtect Helps Businesses Manage Power Outage Risk
Power outages are becoming more common, more unpredictable, and more expensive.
Whether caused by winter weather, aging infrastructure, or grid strain, even short-term outages can disrupt operations, cancel appointments, spoil inventory, and interrupt cash flow. And for many businesses, the most frustrating part is discovering that their insurance doesn’t respond.
That gap is exactly why parametric power outage coverage exists.
This article explains how Adaptive’s GridProtect works, what it covers, what it does not cover, and why more businesses are using it as a financial safety net during outage-prone seasons.
The Problem With Traditional Insurance and Power Outages
Most business owners assume their insurance will help if the power goes out.
In reality, most traditional policies:
Require long waiting periods (often 24–72 hours)
Require proof of physical damage
Exclude short-term outages
Require extensive claims documentation
Reimburse losses only after review and approval
That means a business can lose a full day or two of revenue and still receive no payout at all.
For many small and mid-sized businesses, that gap is where the real financial damage occurs.
What Is GridProtect?
GridProtect is a parametric insurance product offered by Adaptive Insurance designed specifically to address short-duration power outages.
Unlike traditional insurance, GridProtect does not rely on:
Damage assessments
Claims adjusters
Receipts or proof of loss
Instead, it uses objective power-grid data to trigger a payout automatically.
How GridProtect Works
Step 1: A Power Outage Occurs
A power outage impacts the insured business location.
Step 2: Outage Duration Is Verified
Adaptive uses independent, third-party grid data to confirm:
Location of the outage
Length of the outage
Whether the outage meets the policy trigger
Triggers are selected at policy inception and typically include:
8 hours
12 hours
16 hours
20 hours
Step 3: Claim Is Automatically Triggered
Once the outage meets the trigger:
No claim filing is required
No documentation is needed
No adjuster is involved
Step 4: Payment Is Issued
Funds are paid directly to the insured business, usually within 48–72 hours.
The business can use the funds however needed:
Payroll
Lost revenue
Spoiled inventory
Emergency expenses
What GridProtect Covers
GridProtect provides:
Fixed payouts for qualifying power outages
Coverage limits typically ranging from $5,000 to $50,000
Fast, automatic claim processing
Coverage that does not impact loss history
Protection for short-term outages that traditional insurance excludes
This makes it especially useful for businesses that depend on:
Electricity
Refrigeration
Point-of-sale systems
Customer access
Climate control
What GridProtect Does NOT Cover
It’s important to be clear about limitations.
GridProtect does not cover:
Planned or scheduled power outages
Government-mandated shutdowns
Outages occurring before the policy is active
Equipment failure unrelated to grid interruption
Physical property damage
Lost income beyond the policy limit
It is not a replacement for:
Business interruption insurance
Property insurance
Equipment coverage
It is designed to fill a specific gap, not replace existing policies.
Why This Matters During Winter Weather
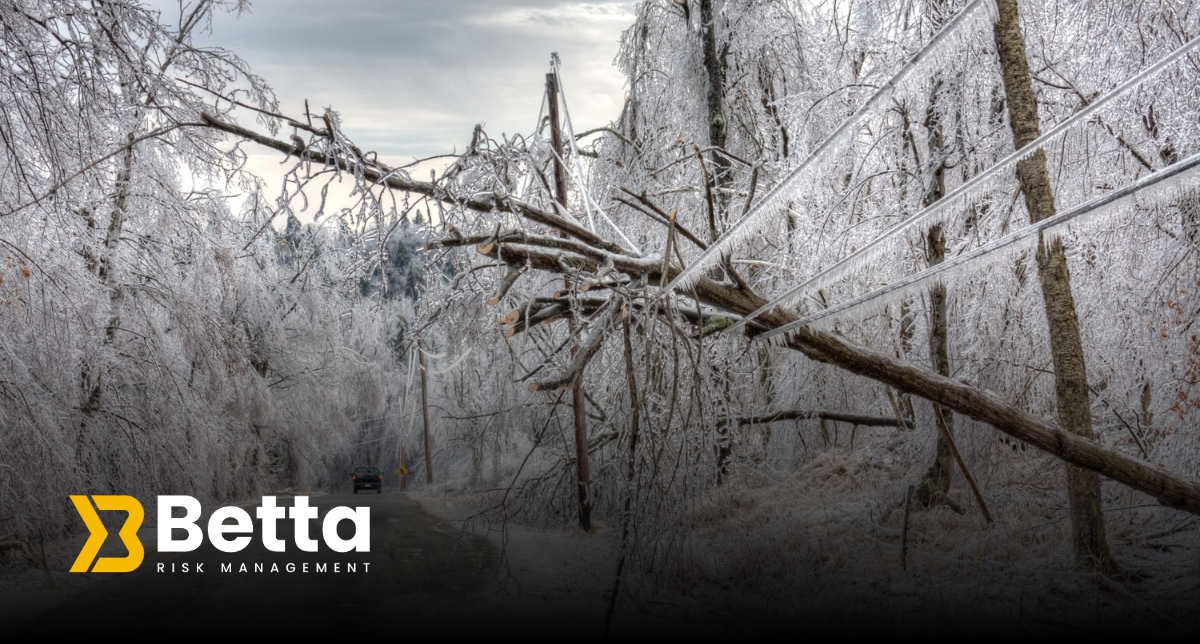
Winter storms are one of the most common causes of power outages in the U.S.
Even when storms are not severe:
Ice and wind can disrupt lines
Restoration timelines vary
Outages often last just long enough to cause losses but not long enough to trigger traditional insurance
GridProtect was built specifically for this kind of event.
It provides:
Predictable protection
Fast liquidity
No disputes over causation or damages
Who This Coverage Is Best For
GridProtect is a strong fit for:
Restaurants and bars
Retail businesses
Medical and dental offices
Warehouses
Service businesses
Any operation sensitive to downtime
Especially those that:
Rely on refrigeration or equipment
Operate on tight margins
Cannot afford multi-day interruptions
Availability
GridProtect is currently available for eligible businesses in the following states:
Georgia (GA)
Florida (FL)
Arizona (AZ)
Colorado (CO)
Illinois (IL)
Indiana (IN)
Kansas (KS)
Maryland (MD)
Minnesota (MN)
Missouri (MO)
New Jersey (NJ)
Nevada (NV)
New York (NY)
Pennsylvania (PA)
Texas (TX)
Utah (UT)
Wisconsin (WI)
Availability may vary by utility region and underwriting criteria.
About Betta Risk Management
Betta Risk Management is an independent insurance and risk advisory firm serving businesses across Florida and South Carolina.
We specialize in identifying coverage gaps that traditional insurance often overlooks and helping business owners implement practical, real-world solutions to manage risk more effectively.
Our focus is not selling policies — it’s helping businesses understand how coverage actually works before something goes wrong.

Next Steps
If your business would be affected by even a short power outage, it’s worth understanding whether parametric coverage makes sense for you.
We can walk you through:
How GridProtect works
Whether your location qualifies
What coverage level makes sense
How it fits alongside your current insurance
📧 [email protected] 📞 (470) 588-5254
A short conversation now can prevent a major disruption later.
Legal Disclaimer
This material is provided for informational purposes only and does not constitute insurance, legal, or financial advice. Coverage availability, limits, terms, and conditions vary by state, carrier, and underwriting guidelines. GridProtect is a parametric insurance product offered by Adaptive Insurance and is subject to the terms, conditions, exclusions, and trigger definitions of the issued policy. Coverage is not retroactive and applies only to qualifying events occurring after policy inception. Always consult a licensed insurance professional to evaluate your specific situation.
